The Landed Cost Trap: How Tariff Surprises Are Erasing the Savings US Companies Thought They Had
Photo: CBP Photography, Public domain, via Wikimedia Commons
The spreadsheet looked convincing. Lower unit costs, favorable lead times, a credible supplier with the right certifications. By the time procurement signed off, the financial case for sourcing overseas appeared airtight. Then the shipment arrived at a US port of entry — and the numbers stopped making sense.
For a growing number of US companies, the moment of reckoning does not happen on the factory floor or during a supplier audit. It happens at customs. And by then, the contracts are signed, the inventory is in transit, and the options for damage control are limited.
Tariff-related cost overruns are not a fringe risk. They are a structural feature of global trade that rewards companies who plan for them — and penalizes those who do not.
Why Classification Errors Carry Such Disproportionate Consequences
Every product entering the United States is assigned a Harmonized Tariff Schedule (HTS) code. That code determines the applicable duty rate, and in many cases, whether additional trade remedies apply. The system sounds orderly. In practice, it is anything but.
HTS classification is interpretive work. A single product can plausibly fall under multiple codes, and the difference between them can mean the difference between a 3 percent duty rate and a 25 percent one. Procurement teams that rely on suppliers, freight forwarders, or internal staff without specialized customs expertise frequently misclassify goods — sometimes by a single digit — and the financial consequences compound with every subsequent shipment.
US Customs and Border Protection (CBP) conducts post-entry audits, and the statute of limitations for duty recovery extends five years. A company that has been importing a misclassified product for three years may face a retroactive assessment that dwarfs the original procurement savings. Interest and penalties apply on top of the underpaid duties. The financial exposure is rarely visible until CBP makes contact.
The challenge is not limited to complex engineered components. Consumer goods, packaging materials, and industrial inputs are all subject to classification disputes. The more a product sits at the intersection of multiple categories — a common occurrence with manufactured assemblies — the greater the interpretive risk.
Anti-Dumping and Countervailing Duties: The Layer Most Procurement Teams Underestimate
Beyond standard tariff rates, the United States maintains an extensive set of anti-dumping (AD) and countervailing duty (CVD) orders covering hundreds of product categories originating from China and other manufacturing economies. These duties exist separately from the Section 301 tariffs that have received considerable attention since 2018, and they are frequently overlooked in cost modeling.
AD/CVD rates are not static. They are reassessed through annual administrative reviews, and the rates applied to specific exporters can shift substantially from one review period to the next. A supplier whose AD rate was negligible when a sourcing decision was made may carry a materially higher rate by the time the goods arrive — or by the time CBP completes a liquidation review.
The mechanics matter here. US importers, not foreign suppliers, bear legal liability for AD/CVD duties. A Chinese manufacturer that quotes a product price has no obligation to factor in the importer's duty exposure. Unless the procurement team independently verifies applicable trade remedy orders — and models the associated costs into landed price calculations — the liability remains invisible until it is not.
Some importers have discovered this dynamic through cash deposit requirements alone. When CBP determines that a product is subject to an AD order, it may require the importer to post a cash deposit equivalent to the estimated duty rate at the time of entry. For companies operating on thin margins, a sudden deposit requirement on a high-volume shipment can create immediate liquidity pressure.
Country of Origin: When the Answer Is More Complicated Than It Appears
Country-of-origin rules add another layer of complexity that procurement teams frequently underestimate. Under US trade law, the country of origin is not simply the country from which a shipment departs. It is determined by where the product underwent its most substantial transformation — a standard that requires legal analysis, not assumption.
For manufactured goods that involve components or processing across multiple countries, origin determinations can be genuinely ambiguous. A product assembled in one country using inputs from another may or may not qualify as originating in the assembly country, depending on the specific transformation rules that apply to its HTS classification.
This matters for two distinct reasons. First, origin affects which tariff rates apply — including whether Section 301 duties, AD/CVD orders, or preferential trade agreement rates are relevant. Second, misrepresentation of country of origin, even when unintentional, can constitute customs fraud under US law. The penalties are severe, and the compliance burden falls on the importer.
Transshipment — the practice of routing goods through a third country to obscure Chinese origin — has attracted sustained enforcement attention from CBP and the Department of Homeland Security. Companies that unknowingly source from suppliers engaged in transshipment face liability exposure that extends well beyond the duty differential.
Building Tariff Strategy Into Supplier Selection
The most effective way to manage tariff risk is to address it before a supplier relationship is formalized, not after the first shipment clears customs. This requires a different sequence of analysis than most procurement processes currently follow.
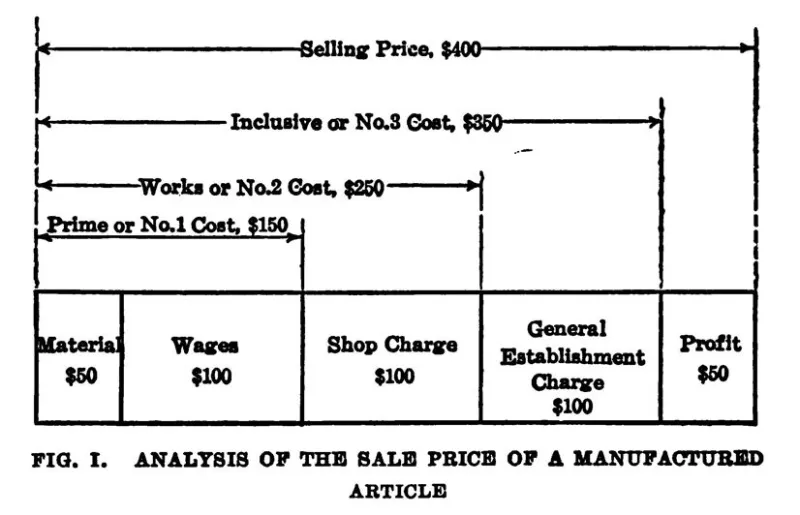
A rigorous landed cost framework begins with HTS classification — not as a logistics formality, but as a substantive analytical step conducted by qualified customs counsel before pricing negotiations conclude. That classification should be cross-referenced against current AD/CVD orders, Section 301 exclusion lists, and any applicable first sale valuation opportunities that could reduce the dutiable value of the goods.
Supplier selection itself should incorporate tariff considerations as a weighted variable. Two suppliers offering comparable unit prices may present meaningfully different landed cost profiles depending on their product's classification, the origin of their inputs, and their history with CBP. A supplier that has been subject to prior enforcement actions or whose goods have been detained at port represents a risk category that unit price comparisons do not capture.
Procurement teams that operate in categories with significant AD/CVD exposure should also maintain awareness of administrative review cycles. Monitoring the annual review process for relevant orders — and adjusting sourcing strategy accordingly — transforms tariff management from a reactive function into a forward-looking one.
The Organizational Shift That Makes the Difference
Tariff strategy is not a customs broker's responsibility alone. It is a cross-functional discipline that requires coordination between procurement, finance, legal, and logistics. Companies that treat it as a post-contract logistics detail consistently absorb costs that their competitors — the ones who plan earlier — avoid.
The financial case for global manufacturing partnerships remains sound when the full cost picture is understood from the outset. The savings are real. The risks are manageable. But they are only manageable when they are accounted for before commitment, not discovered at the port.
For US companies evaluating or expanding global sourcing relationships, the question is not whether tariff complexity exists. It does, and it will continue to evolve as trade policy responds to geopolitical pressures. The question is whether the organization has built the analytical infrastructure to see the true landed cost — and make sourcing decisions accordingly.